Claims & Disputes
Public adjusters: what they do and when to hire one
A licensed professional who represents the policyholder rather than the insurer, paid a percentage, useful in some situations and not others.
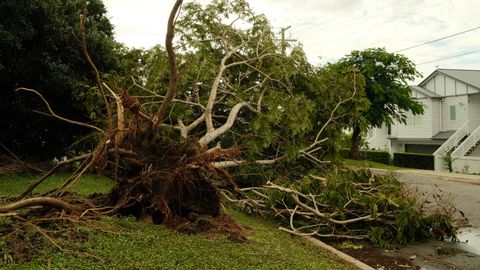
There are three kinds of adjuster. The staff adjuster works for the insurer. The independent adjuster is contracted by the insurer. The public adjuster is hired by and works for the policyholder.
What a public adjuster does
Reviews the policy and identifies applicable coverages.
Documents and measures the damage, frequently in more detail than an insurer's adjuster.
Prepares a detailed estimate and a proof of loss.
Compiles the contents inventory.
Negotiates with the insurer's adjuster.
Manages the process, deadlines and correspondence.
They cannot provide legal advice or litigate. Where a coverage dispute becomes legal, an attorney is required.
The fee
Typically a percentage of the settlement, commonly in the range of five to fifteen percent, varying by state, by claim size and by when in the process they are engaged.
Several states regulate the maximum fee, and some cap it lower for catastrophe claims or prohibit solicitation within a period after a disaster.
Fees are usually lower for very large claims and higher for small ones.
Some charge a percentage of the total settlement including amounts the insurer had already offered before they were engaged, which is worth negotiating — a fee on the increase achieved is a fairer structure and is sometimes available.
When they are worth it
Large and complex losses. A total or near-total loss involving structure, contents, additional living expenses and code upgrades has many components, and thoroughness produces materially better outcomes.
Where the initial estimate seems substantially low and you lack the expertise to argue it line by line.
Commercial claims, particularly involving business interruption, where the calculation is technical.
Where you cannot manage the process — because you are displaced, working, caring for family, or dealing with the aftermath of the event itself.
The time cost of a major claim is substantial. People underestimate it consistently.
Where the claim has stalled and direct efforts have not moved it.
When they are not
Small claims, where the fee consumes a meaningful share of a modest settlement.
Straightforward claims being handled promptly and fairly, where the settlement offer is reasonable.
Where the dispute is about coverage rather than amount. Whether a loss is covered is a legal question; a public adjuster cannot resolve it and an attorney can.
Early in a claim that is proceeding normally. Engaging one before the insurer has even inspected means paying a percentage on a settlement that may have been reached anyway.
It is generally reasonable to let the process begin, see the insurer's estimate, and then decide.
Choosing one
Verify the license with the state insurance department. Public adjusters are licensed in most states, and unlicensed operators appear after disasters.
Check for complaints with the regulator.
Ask for references from clients with similar claims.
Ask about experience with your specific type of loss.
Read the contract carefully. The fee percentage and what it applies to. The cancellation provision, since most states require a right to cancel within a few days. Whether they have authority to settle without your approval, which they should not. And whether the fee applies to advance payments already made.
Be wary of solicitation after a disaster. Door-to-door approaches following a catastrophe are restricted in many states and are a common vector for both incompetence and fraud.
Take time. A contract signed in the days after losing a home is signed under pressure.
The contractor complication
A related issue.
Some contractors offer to handle the insurance claim, sometimes describing themselves as working with the insurer.
In most states, negotiating a claim on a policyholder's behalf for compensation requires a public adjuster license. Contractors doing so may be acting unlawfully.
Assignment of benefits agreements, where a contractor takes over the claim rights, have been the subject of substantial abuse and litigation in several states, with legislation restricting them.
Be very cautious about signing anything transferring your claim rights, and read what you sign.
Doing it yourself well
Many claims are handled fine by the policyholder, and the skills are learnable.
Read the policy in full. Document extensively. Obtain independent itemized estimates. Compare line by line against the insurer's estimate. Identify omissions — code upgrades, matching, debris removal, additional living expenses. Communicate in writing. Escalate methodically.
Where that produces a reasonable settlement, you have saved the fee.
Where it does not, engaging a public adjuster later is still available, and by then you will know whether the gap justifies the cost.
General information about claims representation, not insurance or legal advice. Public adjuster licensing, fee limits and permitted activities vary substantially by state. Verify licensing with your state insurance department.
Also by Grace Mbeki
- A yearly insurance review across everythingClaims & Disputes
- Choosing an insurer, not just a priceClaims & Disputes
- Homeowners coverage: the annual checkHome & Property
- The annual auto policy reviewAuto Insurance