Home & Property
Getting insured in a hard market
In several states, homeowners coverage has become expensive, restricted or genuinely difficult to obtain, and the options are narrower than they were.
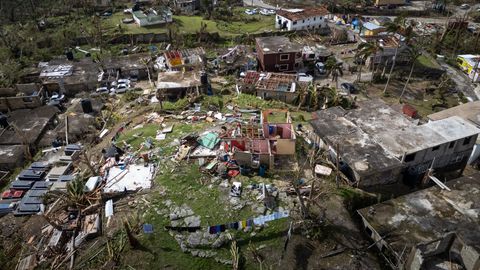
Property insurance markets cycle between soft conditions, with ample capacity and competitive pricing, and hard conditions, with restricted capacity and rising prices.
Several regions have experienced sustained hard market conditions driven by catastrophe losses, reinsurance costs and construction cost inflation.
What a hard market looks like
Premiums rising sharply at renewal.
Deductibles increasing, particularly percentage deductibles for wind, hail and hurricane.
Coverage narrowing — roof settlement moving to actual cash value or a payment schedule, new exclusions, reduced sublimits.
Insurers ceasing to write new business in a state or region.
Non-renewals of existing policies, sometimes in large numbers.
Insurers withdrawing entirely from a market.
If you receive a non-renewal notice
Note the effective date and the required notice period, which is regulated in most states and gives you time to find alternatives.
Ask the reason. Many states require it to be stated. The reason determines what you can do about it.
If it is property-specific — roof age, prior claims, condition — some of it may be addressable.
If it is a book-wide withdrawal from the state or region, it is not personal and not fixable.
Do not let coverage lapse. A gap makes replacement coverage harder and more expensive, and if you have a mortgage the lender will force-place coverage, which is expensive and protects only the lender.
Where to look
An independent agent who represents multiple carriers, rather than a captive agent representing one.
In a hard market, knowing which carriers are still writing in your area is the whole job, and that knowledge is local and current.
Surplus lines carriers, which are not admitted in the state and are not subject to the same rate and form regulation.
They write risks the standard market will not. Coverage terms vary considerably and are frequently narrower.
Important: surplus lines policies are generally not protected by state guaranty funds, so the insurer's financial strength matters more than usual.
The state residual market. Most states have a mechanism of last resort — a FAIR plan, a windstorm pool, or a state-established insurer.
These provide coverage where the private market will not. They are typically more expensive with narrower coverage — many FAIR plans cover a limited set of perils and may not include liability or theft.
Where a residual market policy is used, a separate policy is frequently needed to fill the gaps, sometimes called a difference in conditions policy.
Making the property more insurable
Several factors drive both availability and price, and some are within your control.
Roof age and condition. The single largest factor in many markets. Insurers frequently decline properties with roofs above a certain age, or restrict coverage on them.
Replacing an aging roof, particularly with impact-rated materials, can restore insurability and reduce premium substantially.
Wildfire mitigation, in exposed areas. Defensible space, ember-resistant vents, non-combustible roofing and siding, and clearance around structures.
Several states have established mitigation standards with associated insurer requirements to recognize them.
Wind mitigation, in hurricane-exposed areas. Roof-to-wall connections, opening protection, roof deck attachment, secondary water barriers.
Wind mitigation inspections are inexpensive and can produce substantial credits in states that mandate them.
Elevation, in flood-prone areas, which affects flood premiums considerably.
Claims history. Prior claims affect insurability, which is an argument for not claiming small losses that you could absorb.
Updated systems. Electrical, plumbing and heating updates on older homes.
Managing the cost
Raise the deductible, with reserves to match. This is frequently the most effective lever.
Bundle auto and home, which remains one of the larger available discounts.
Review coverage limits against actual replacement cost, in both directions. Being underinsured is dangerous; being insured for well above replacement cost is wasteful.
Ask about every discount, including alarm systems, water leak detection, new roof, updated systems, claims-free history, and paid-in-full.
Shop at every renewal in a hard market, which is more work and more necessary.
What not to do
Do not reduce coverage to a level that leaves you exposed to the loss that would actually ruin you.
The purpose of the policy is the catastrophic loss. Economizing by reducing the dwelling limit below replacement cost, or dropping liability limits, defeats it.
Economize on deductibles and on the frequency of small claims instead.
And do not go uninsured. Where the only available option is expensive and narrow, it is still the difference between a bad year and a permanent one.
General information about insurance markets, not insurance advice. Availability, residual market mechanisms and mitigation programs vary substantially by state. Consult a licensed independent agent and your state insurance department.
Also by Aisha Rahmani
- What we would tell someone buying their first policiesClaims & Disputes
- Small claims court and other routes when appeals failClaims & Disputes
- Disability claim documentation over the long termDisability & Income
- Insurance when you work from homeHome & Property