Home & Property
Why Roof Age Decides So Much On A Home Policy
Roof age and material now drive eligibility and settlement terms on homeowners policies, because roofs generate a large share of property claims and depreciate visibly.
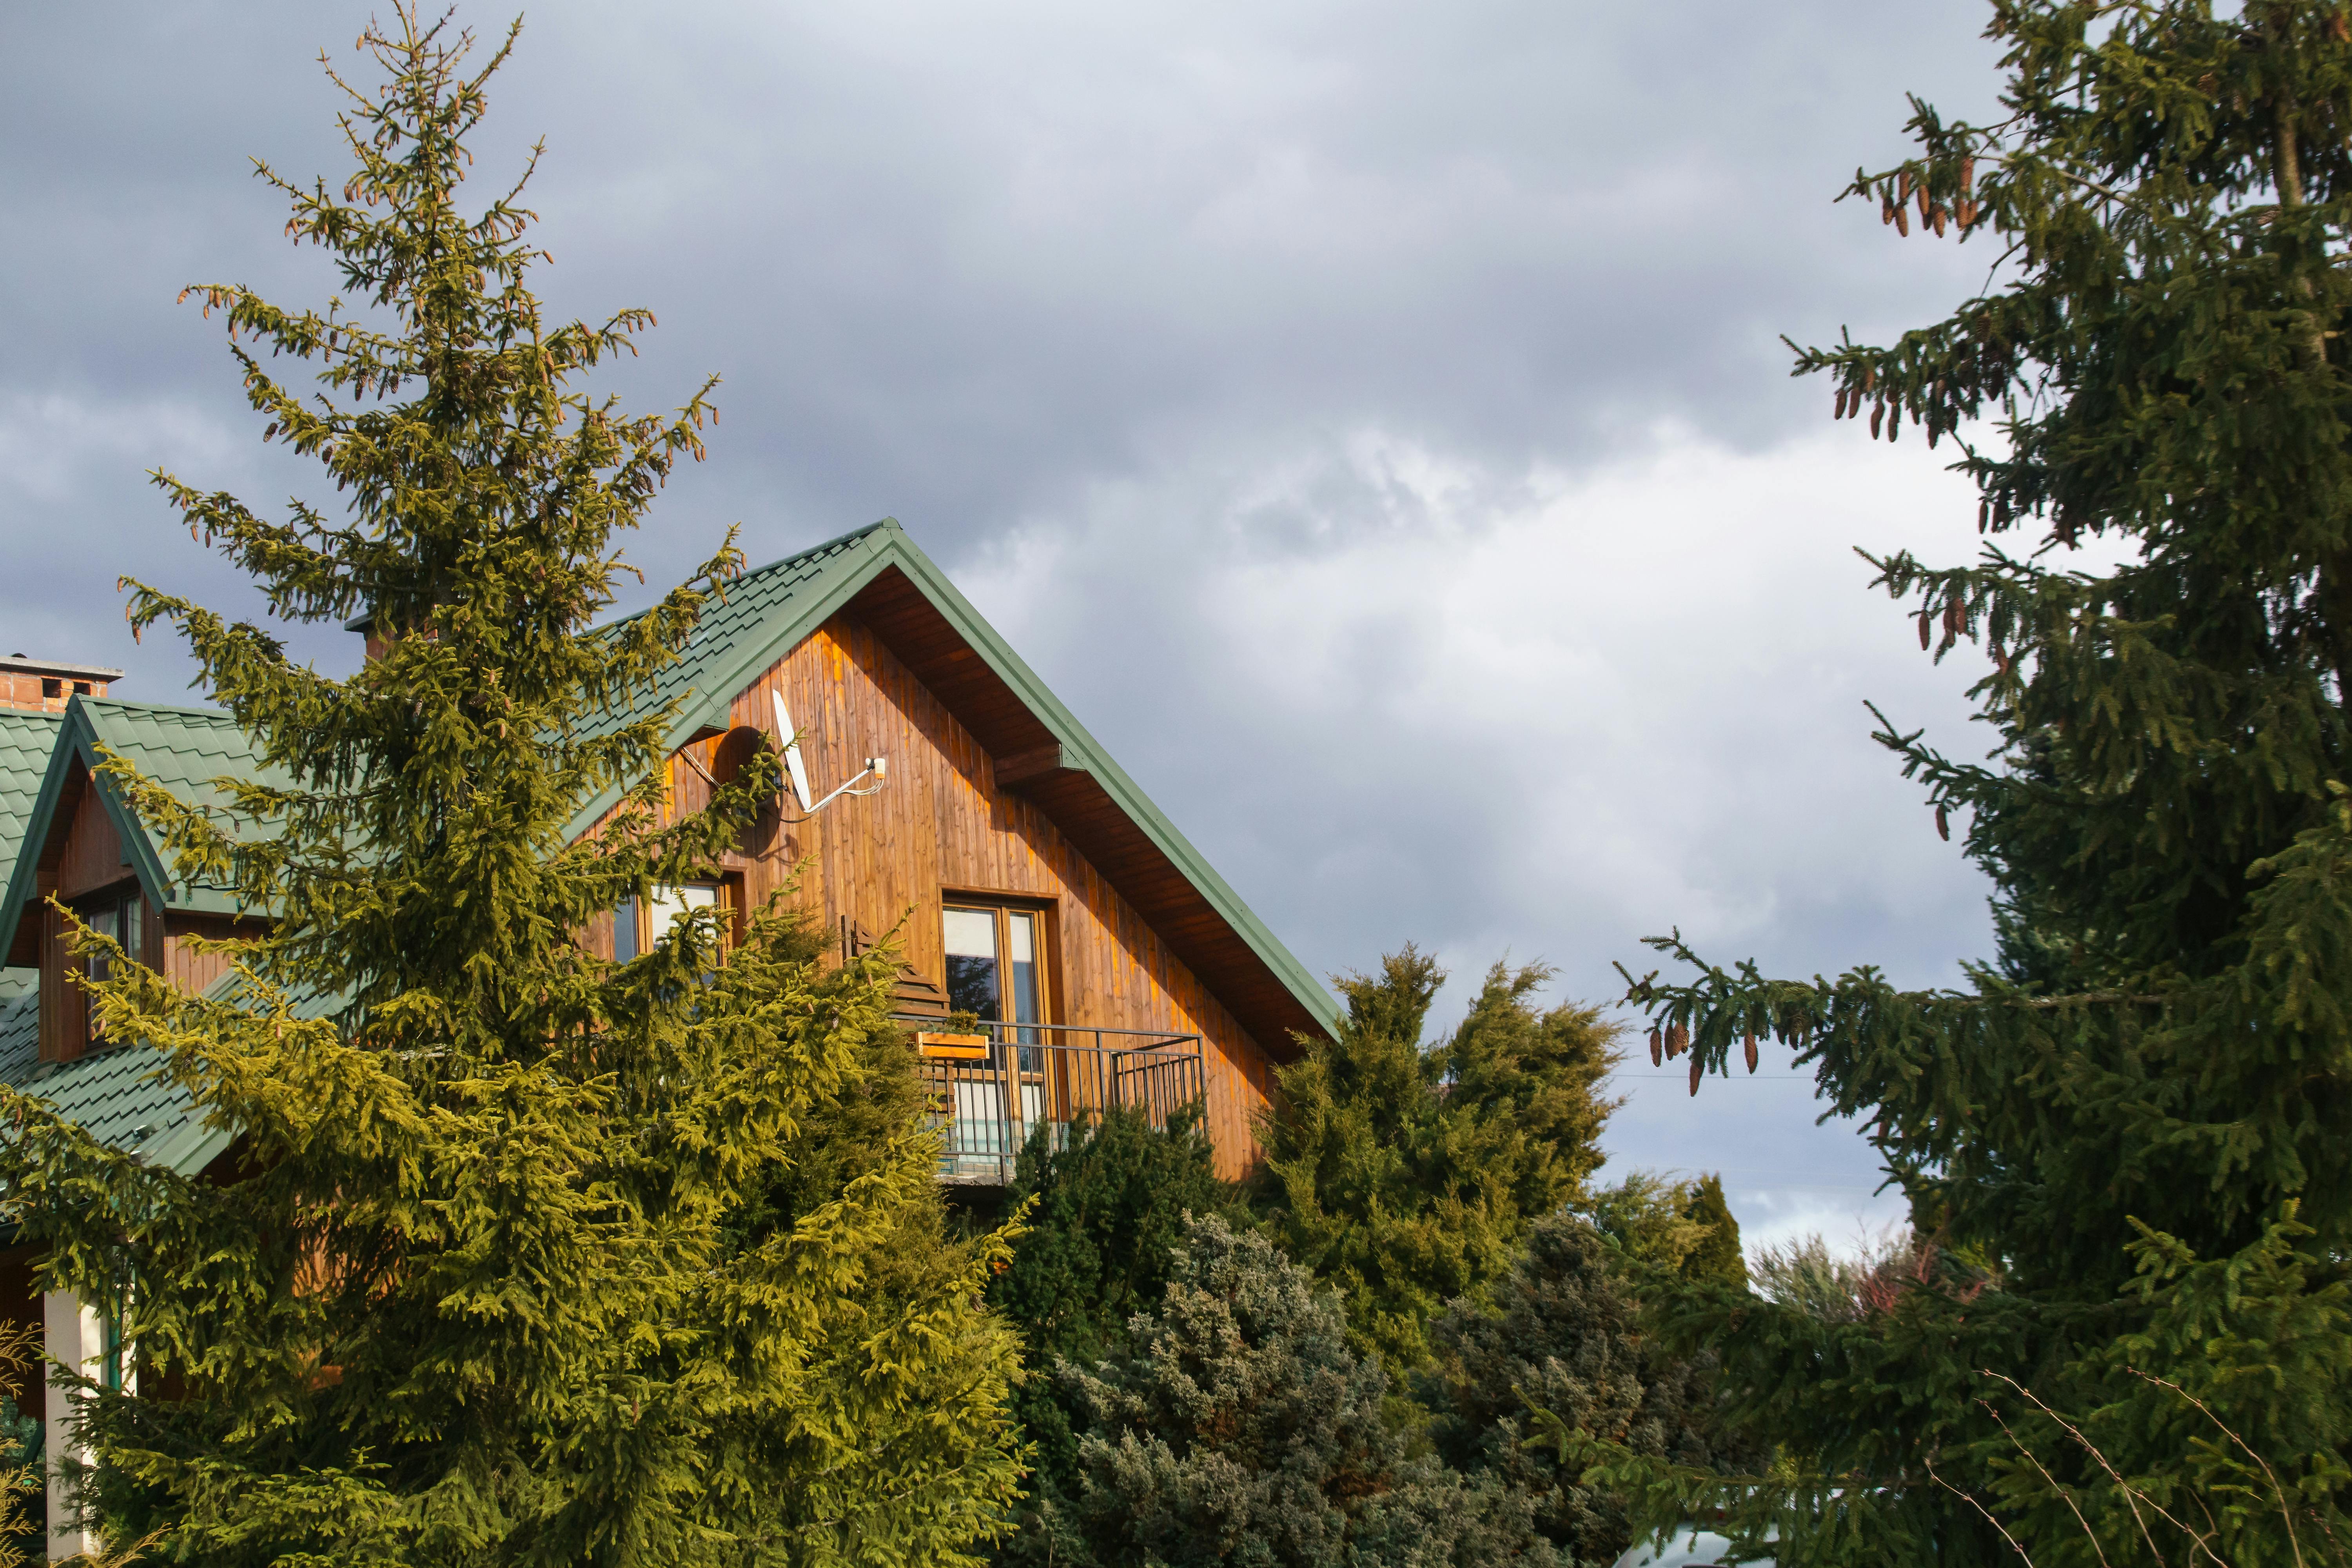
Insurers ask about roof age and material before almost anything else on a homeowners application. The roof is the building component most exposed to loss and the one whose condition most reliably predicts claims.
Roofs carry disproportionate claim activity
Wind, hail and water intrusion losses usually begin at the roof, and a compromised roof turns a weather event into an interior claim as well.
Because these losses are weather-driven, they arrive in concentrated events affecting many homes at once, which shapes how insurers manage the exposure.
Roof condition is also one of the few structural elements that can be assessed from outside during an inspection or from aerial imagery.
Age is used as a proxy for condition
Materials have expected service lives, and the probability of failure rises as a roof approaches the end of that life.
Insurers therefore set eligibility rules by age and material, and those rules tighten in regions with severe convective weather.
An older roof may make a home ineligible for a preferred program, eligible only with conditions, or eligible only for a policy with different settlement terms.
Settlement terms often change with age
Many policies now settle older roofs on an actual cash value basis, deducting depreciation, while newer roofs are settled on a replacement cost basis.
Some forms use a schedule that reduces the payable percentage as the roof ages, stated as an endorsement attached to the policy.
These provisions are set out in the policy documents, and reading them is the only way to know which basis applies to a particular roof.
Material matters as much as age
Different materials perform differently against hail and wind, and some qualify for credits where they meet recognized impact resistance standards.
Underwriting also considers roof geometry and attachment method, because these affect uplift resistance in high wind.
In some regions, building codes now require specific roofing practices, and ordinance and law provisions determine how those requirements are funded after a loss.
Documenting a roof before it matters
Keeping the replacement invoice, permit and photographs gives an insurer evidence of age and workmanship rather than an estimate from imagery.
Inspection reports after a storm establish condition at a point in time, which becomes relevant when later damage must be dated.
Roof settlement rules and eligibility standards vary by state and change over time, and whether any particular roof loss would be covered depends on the policy and facts; a licensed agent or the state insurance department can explain what applies.
Also by Grace Mbeki
- A yearly insurance review across everythingClaims & Disputes
- Choosing an insurer, not just a priceClaims & Disputes
- Homeowners coverage: the annual checkHome & Property
- The annual auto policy reviewAuto Insurance